Homeownership is an important financial milestone, but protecting a property involves more than maintaining the roof, managing mortgage payments, and keeping up with routine repairs. Understanding home insurance exclusions matters because a standard policy may not cover every type of damage, loss, or liability. Effective asset protection also involves considering how unexpected expenses could affect household finances, long-term goals, and estate planning. By understanding policy limitations and reviewing coverage regularly, homeowners can take practical steps to reduce financial uncertainty and preserve the value of their assets.
What Are Home Insurance Exclusions?
Home insurance exclusions are specific situations, events, or types of damage that an insurance policy does not cover. Although homeowners insurance generally protects against certain unexpected losses, the scope of protection depends on the policy language, coverage limits, deductibles, and applicable conditions.
For example, a policy may cover damage from a sudden, accidental plumbing failure while excluding damage from gradual leaks or neglected maintenance. Understanding these distinctions before filing a claim can help prevent unexpected out-of-pocket expenses.
Why Reviewing Exclusions Matters
Uninsured property damage can strain savings, disrupt financial plans, and create unexpected repair costs. Some homeowners assume their policy provides comprehensive protection without checking the exclusions and endorsements.
A regular policy review helps identify coverage gaps, clarify responsibilities, and determine whether additional protection is appropriate. These steps support a broader asset protection strategy by helping homeowners prepare for risks that could otherwise affect their financial stability.
Common Insurance Exclusions Homeowners Should Review
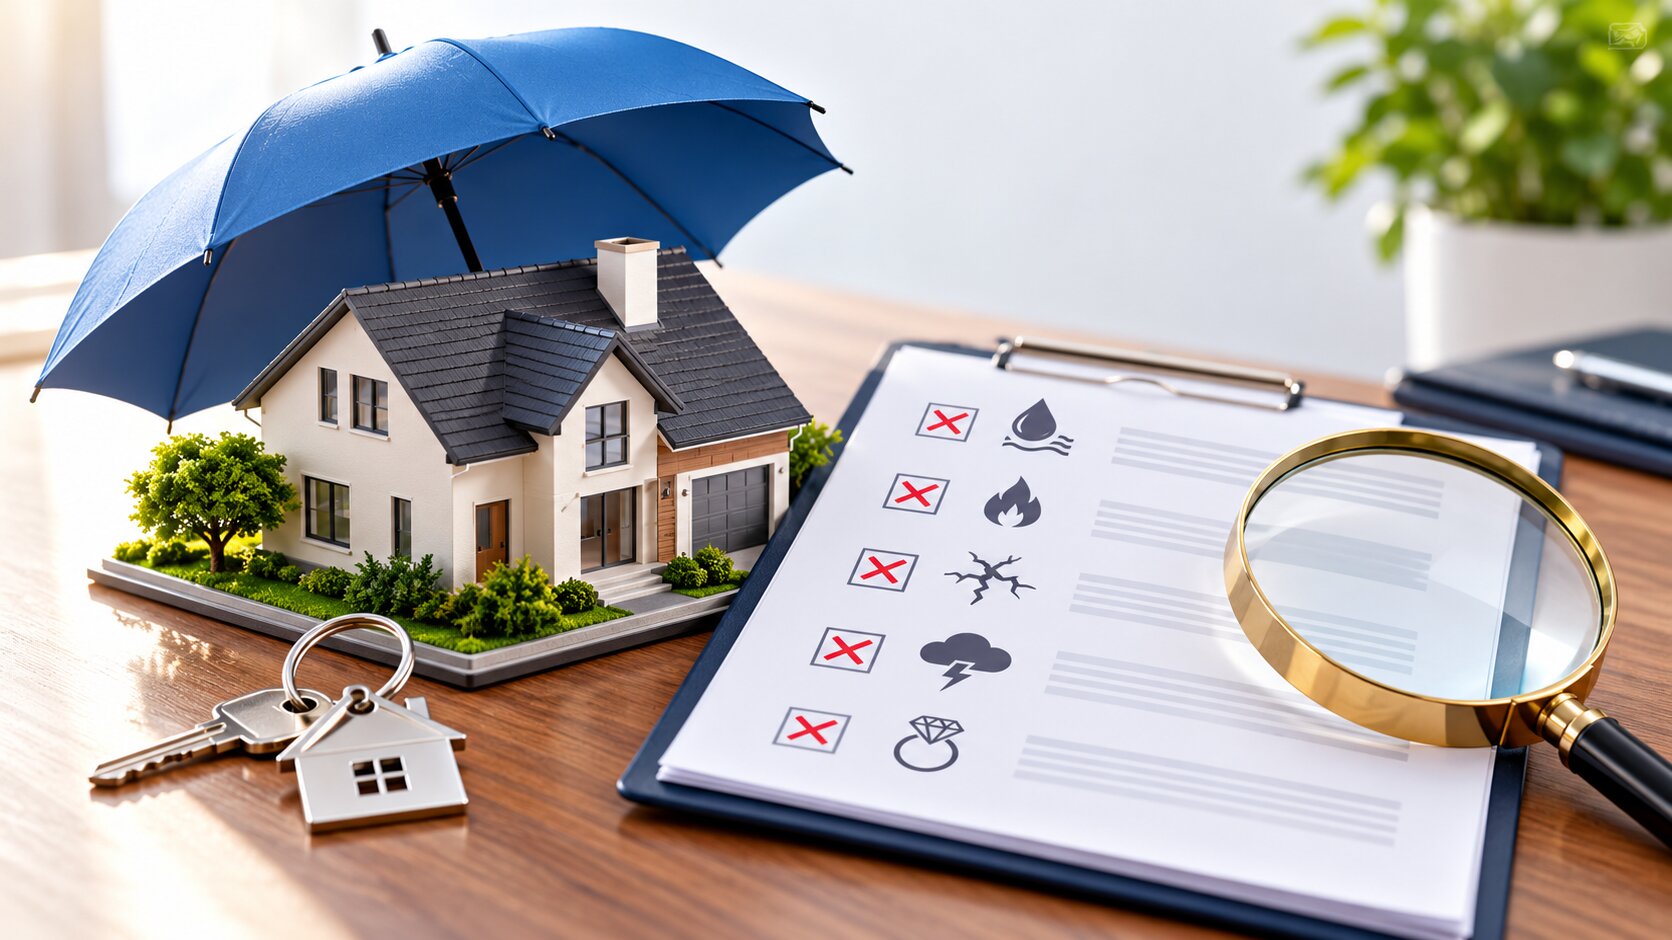
Not all home insurance policies have identical exclusions. Pay attention to the following areas when reviewing coverage documents and discussing potential risks with an insurance professional.
Flood Damage
Standard homeowners insurance policies generally exclude flood damage, although coverage depends on the policy wording and circumstances. Flooding may result from overflowing rivers, heavy rainfall, storm surges, or water accumulating on normally dry land.
Homeowners in flood-prone areas should review their exposure and determine whether separate flood insurance is appropriate. It is also important to understand waiting periods, coverage limits, and exclusions that may apply to basements, personal belongings, or certain building components.
Earthquakes and Ground Movement
Standard homeowners policies may exclude earthquakes, landslides, sinkholes, and other forms of ground movement. Coverage availability and definitions vary by insurer and location. Homeowners should also understand relevant property tax considerations when reviewing their broader property-related finances.
Homeowners concerned about these risks can ask about separate policies or endorsements. Reviewing these options before an event occurs can help clarify the financial resources available for rebuilding, structural repairs, and replacing damaged possessions.
Wear and Tear or Poor Maintenance
Roof deterioration, corrosion, mold from long-term moisture problems, and damage from neglected repairs may fall outside policy protection, depending on the circumstances. Regular inspections and timely maintenance can help homeowners identify problems before they become more expensive. Keeping receipts, inspection reports, and repair records also provides useful documentation when questions arise about the cause of damage.
Sewer Backups and Water Damage
Water-related claims can be complicated because policies may treat sudden plumbing failures, sewer backups, and gradual leaks differently. Some policies cover certain sudden and accidental water damage but exclude sewer or drain backups unless you purchase additional coverage.
Homeowners should review how their policy defines covered water damage and ask whether a water-backup endorsement is available. Understanding these distinctions can help prevent assumptions about coverage when repairs are needed.
High-Value Personal Belongings
Standard homeowners policies often impose special limits on valuable possessions, including jewelry, collectibles, artwork, and certain electronics. A covered event may still result in limited reimbursement if an item’s value exceeds the applicable sublimit.
Homeowners with valuable belongings should review personal property limits, documentation requirements, and valuation methods. Scheduled personal property coverage or another suitable endorsement may provide additional protection for qualifying items.
Mold, Termites, and Pest Damage
Damage caused by termites, rodents, insects, and mold may be excluded, particularly when it develops gradually or results from inadequate maintenance. However, coverage can depend on the cause of the damage and the policy’s specific wording.
Homeowners should address moisture problems promptly, schedule pest inspections when appropriate, and maintain records of preventive work. These measures can reduce avoidable property damage and help clarify the circumstances surrounding a future claim.
Intentional Damage and Certain Liability Risks
Insurance generally excludes losses the policyholder intentionally causes. Some policies also contain specific liability exclusions involving certain animals, home-based activities, or other risks.
Reviewing personal liability provisions is especially important for homeowners with pools, rental arrangements, or significant personal assets. Discuss additional liability coverage with an insurance professional when existing limits don’t match the household’s exposure.
How Insurance Exclusions Affect Asset Protection
Unexpected property losses can affect more than the home itself. Repair costs may reduce emergency savings, delay retirement goals, and add pressure to other financial commitments. Reviewing insurance coverage gaps is one practical step homeowners can take when evaluating the risks that could affect their personal assets.
A practical asset protection strategy considers insurance alongside savings, liability exposure, and long-term financial planning. Homeowners can also review how property ownership fits into their broader estate planning goals.
Connect Insurance Reviews With Tax and Financial Planning
Insurance proceeds, property improvements, casualty losses, and ownership arrangements can have different tax implications depending on the circumstances. Homeowners evaluating these issues may benefit from professional tax planning and tax consulting services. Private Tax Solutions can help individuals understand relevant tax considerations as part of their broader financial planning needs.
Individual tax services may also be useful when reviewing property-related transactions, inheritance considerations, or other financial changes. Tax treatment depends on applicable rules and individual circumstances, so homeowners should consult qualified tax professionals before making decisions based on assumed tax benefits. Professional tax planning and advisory can help homeowners evaluate relevant tax considerations when property transactions or other financial changes occur.
Steps to Review Your Home Insurance Policy
A structured review can help homeowners identify potential gaps before a loss occurs.
- Read the exclusions section: Check which events, property types, and circumstances are excluded.
- Compare coverage limits: Confirm that dwelling coverage reflects estimated rebuilding costs and that personal property limits suit your belongings.
- Ask about additional coverage: Discuss flood protection, earthquake coverage, sewer backups, and scheduled valuables where relevant.
- Document your property: Keep photos, receipts, appraisals, and renovation records in a secure location.
- Review your policy annually: Reassess coverage after major renovations, significant purchases, changes in occupancy, or other important life events.
- Coordinate your financial plans: Consider how potential uninsured losses could affect savings, tax planning, and estate planning arrangements.
These steps can help homeowners make informed decisions without assuming that every exclusion requires a separate policy.
Frequently Asked Questions
What are the most common home insurance exclusions?
Common exclusions include flood damage, earthquakes, normal wear and tear, neglect, certain pest damage, and some types of water backup. Beyond liability limits, homeowners should also understand common home insurance exclusions that could leave them responsible for certain property losses.
Can additional coverage protect against insurance exclusions?
Yes. Depending on availability and eligibility, homeowners may purchase separate policies or endorsements for risks such as flooding, earthquakes, sewer backups, and high-value belongings.
How often should homeowners review insurance exclusions?
Review your policy at least annually and whenever significant changes occur, including renovations, valuable purchases, or changes in property use.
How do insurance exclusions affect asset protection?
Uncovered losses may require homeowners to use personal savings or other assets to pay for repairs. Reviewing exclusions can help identify financial risks and evaluate suitable coverage options.
Can tax planning help homeowners protect their assets?
Tax planning can help homeowners understand the potential tax consequences of property transactions, inheritance, and other financial decisions. A qualified tax professional can explain how relevant rules apply to individual circumstances.
Conclusion
Understanding insurance exclusions is an important part of responsible homeownership. Reviewing policy limitations, maintaining property records, and considering additional coverage can help reduce uncertainty and support long-term financial stability. Combining insurance reviews with thoughtful asset protection, tax planning, and estate planning can provide a more complete view of household financial needs. Contact Private Tax Solutions to discuss tax-related considerations and explore how professional tax guidance can support your broader financial goals.
